

Acorns Early: Kids Money App

- 534.00 Reviews
- 4.5
- Downloads
- 100,000+
Our take on Acorns Early: Kids Money App from Appgk
I found Acorns Early: Kids Money App most interesting as a family finance tool rather than a miniature banking game. It is designed to help parents introduce saving and investing habits to children and teenagers, while keeping the experience approachable enough for everyday conversations about money. I would not treat it as a complete financial education course, but I can see why a parent might want a simple starting point instead of handing a young person a complicated investing platform.
The app sits in the finance category and is developed by Acorns. It is free to download, rated for Everyone, and supports devices running Android 7.0 or later. Its current version is 9.7.0, and it was released on November 8, 2024. Those details make it fairly easy to try on an older Android phone, although the actual experience will still depend on the device, display, and the way a family intends to use it.
How the experience feels for different users
Readability and navigation for parents, children, and teenagers
My first impression is that the concept is easier to understand than the financial language often found in adult investing apps. A parent can approach it with a straightforward goal: use an investing plan as one part of a child’s broader money routine. That framing matters because younger users can quickly lose interest when an app begins with charts, account terminology, and dense explanations.
I would still expect the parent to lead the first session. An app aimed at children and teens needs more than simple wording; it needs a clear division between what the adult manages and what the young person is meant to understand. Families should decide in advance whether the child is only learning concepts, checking progress, or taking part in regular saving discussions. That small conversation prevents the app from becoming something the child opens once and then forgets.
Best Parts of Acorns Early: Kids Money App
Things to Keep in Mind About Acorns Early: Kids Money App
The most useful reading strategy is to take one idea at a time. Instead of trying to explain investing, saving, spending, and long-term growth in one sitting, I would use a short routine: open the app together, identify the purpose of the plan, and ask the child to explain it back in their own words. This is a more inclusive approach for children who process information slowly, dislike financial vocabulary, or become overwhelmed by too many choices.
Teenagers may want more control and detail than younger children. That creates a natural tension. A simplified interface can make the first steps less intimidating, but it may feel limited to a teenager who already understands budgets, risk, and account balances. I would use the app as a conversation aid rather than assuming it can satisfy every level of financial curiosity.
News and Features Related to Acorns Early: Kids Money App

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
For parents, navigation is also about confidence. Money apps can make adults nervous when they are unsure which action is educational and which action has a real financial consequence. I recommend exploring the experience privately before introducing it to a child, then agreeing on a regular review time. A calm weekly or monthly check-in is more useful than repeatedly monitoring every small change.
Motor and sensory considerations in daily use
A finance app for families should be comfortable to use on different screens and in different physical situations. Someone may open it on a small phone, while travelling, with one hand, or while helping a child who needs extra time to respond. I would avoid assuming that every user can tap quickly, read small text, or distinguish visual changes without assistance.
Don't want to read the full review?
For children with motor difficulties, a parent can make the experience less demanding by holding the phone steady, using a larger display when available, and allowing the child to answer verbally while the adult handles navigation. That does not remove the child from the learning process; it separates the physical task of operating the device from the financial task of understanding the decision.
Sensory preferences also vary. Some children concentrate better in a quiet room, while others need a short activity with frequent breaks. I would not turn the app into a lesson during a noisy family moment or a rushed trip. Financial concepts already require attention, and a busy setting can make an otherwise clear screen feel difficult to follow.
Screenshots
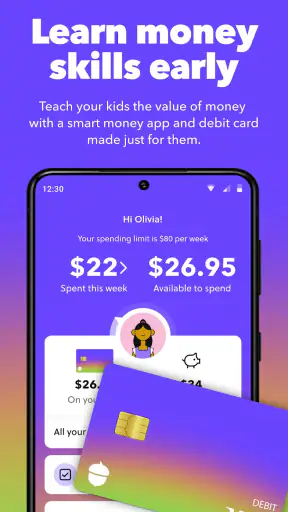
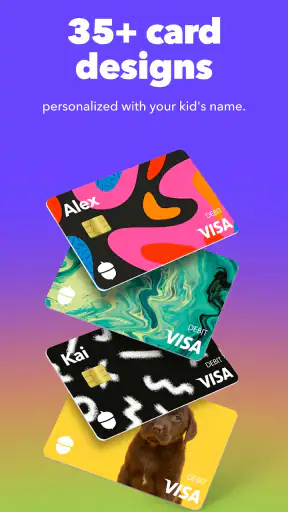
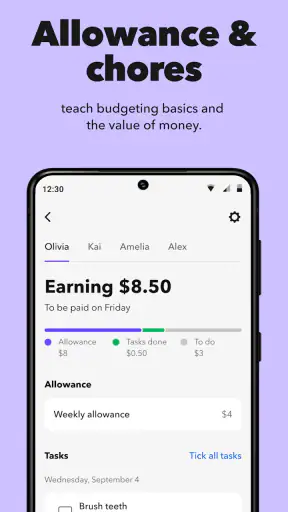
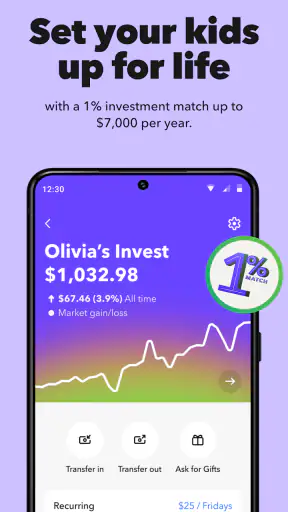
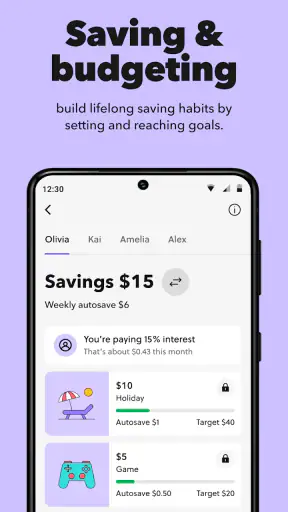
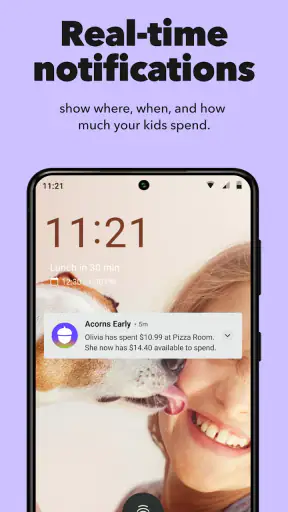
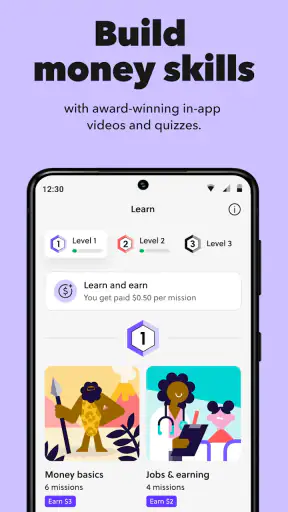
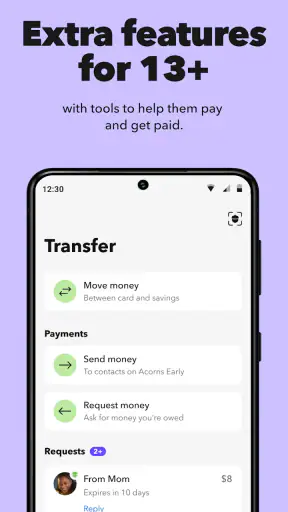
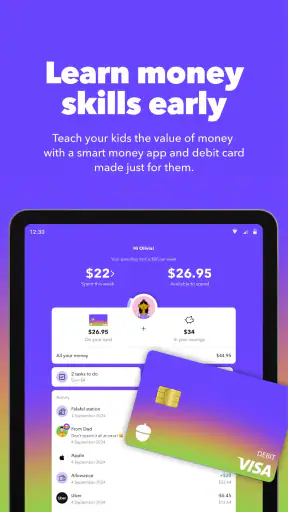
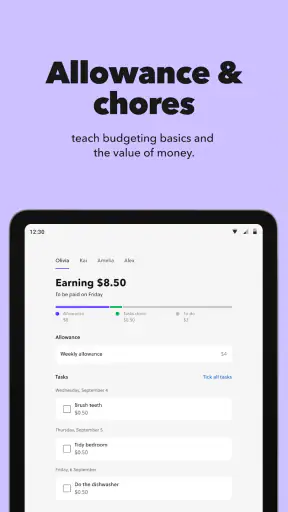
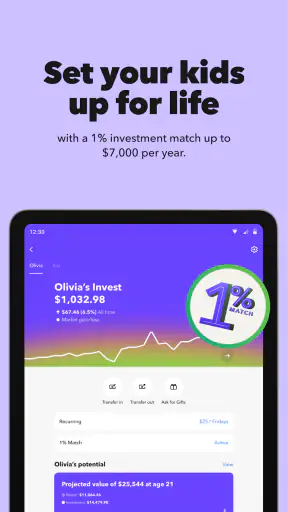
Visual simplicity is particularly important when discussing money with a child who has dyslexia, reduced vision, attention difficulties, or another reading-related need. I would encourage families to read important wording aloud, enlarge the device display where appropriate, and avoid relying on color alone when explaining progress. These are practical habits rather than claims about any formal accessibility certification.
Voice input, screen readers, contrast behavior, text scaling, and gesture support can differ by device and operating system. I would test the app with the specific phone a child will use instead of assuming that Android’s accessibility tools will behave identically everywhere. If a child cannot comfortably complete a task, the right response is to change the shared workflow, not to pressure them to use the app independently.
Situational access: where the app fits and where it does not
The strongest use case I see is a parent and child sitting together after a real money event. Imagine a teenager receives money for a birthday or a small job. Rather than immediately dividing it into vague categories, the parent can use the investing plan as a prompt to discuss what portion is for a near-term goal and what portion is intended for the future. The app becomes part of a decision, not the entire lesson.
Another useful situation is a monthly family review. A parent can ask what the child remembers, whether the plan still matches the family’s goal, and what questions have appeared since the last conversation. This is more accessible for children who struggle with spontaneous questions because the routine gives them a predictable opportunity to speak.
I also think the app can help when adult and child have different levels of financial knowledge. A parent does not need to present themselves as an expert. They can say, “Let’s understand this together,” then focus on the purpose of long-term investing, the possibility of change over time, and the difference between learning and making a promise about future results.
It is less suitable for a child who expects a fast, game-like reward loop. Investing does not provide the immediate feedback of a typical entertainment app, and a young user may find the subject too abstract without a real-world example. In that case, a physical savings goal, allowance chart, or supervised budgeting exercise may be a better first step, with Acorns Early introduced later.
It is also not my first choice for an adult who wants detailed independent portfolio analysis. The app’s family focus is its appeal, but that same focus means it should not be judged as a replacement for a full-featured investing platform. Adults who need advanced research, tax planning, or highly specific control may be better served by a product built for their own financial decisions.
Practical trade-offs and remaining barriers
The biggest barrier is not necessarily the interface; it is the subject itself. A child can read every label and still misunderstand risk, time horizon, or the fact that investing is not the same as guaranteed saving. Parents need to add that explanation. I would never leave a young user to interpret financial progress without context, especially if a screen shows movement that could be mistaken for a reward or a promise.
There is also a difference between access and independence. A child may be able to view information but still need an adult to explain it, approve decisions, or connect it to household goals. That is not automatically a weakness, because family finance should involve appropriate supervision. Still, families should be honest about the level of autonomy they want. The app works best when expectations are clear.
Another friction point is attention. A child who has difficulty with working memory may forget what a particular screen means between sessions. I would keep a simple paper note beside the device with three plain-language reminders: what the plan is for, when the family reviews it, and which questions to ask. This reduces the need to remember the entire structure of the app.
Language can be a barrier even when the wording is relatively friendly. Financial terms often carry more meaning than they appear to. I would pause at words such as investing, growth, risk, and long term, then use a household example. For a multilingual family, discussing the concept in the language the child understands best may be more valuable than insisting that every explanation happen inside the app.
Families should also consider whether a child has reliable access to a compatible device and a quiet moment to use it. Shared phones, limited data, poor vision, hand fatigue, or inconsistent internet access can all change the experience. The app should support the family routine, not become another requirement that excludes a child who cannot use the device in the expected way.
How it compares with ordinary alternatives
Compared with a basic savings jar, Acorns Early offers a more direct way to introduce the idea that money can have a long-term purpose beyond immediate spending. A jar is wonderfully visible and tactile, though, so it may work better for a younger child or anyone who learns through physical actions. I would combine the two rather than treating them as competitors: use a tangible short-term goal and the app for a longer conversation.
Compared with a spreadsheet, the app is likely to feel more approachable for a family that does not enjoy building formulas or maintaining manual records. A spreadsheet can be more flexible and transparent for an older teenager, especially one who wants to model different scenarios. The trade-off is that a spreadsheet demands more effort and does not naturally create a child-friendly routine.
Compared with a standard adult investing app, Acorns Early has a clearer family-learning angle. An adult platform may offer more detail, but that detail can distract from the first lesson. I would choose the adult alternative when the teenager is ready to study investments independently and the parent wants granular control. I would choose Acorns Early when the priority is establishing a shared habit and vocabulary.
Compared with a budgeting app, this product addresses a different part of financial wellness. Budgeting tools are usually better for tracking income, spending, and short-term limits. Acorns Early is more relevant when the family wants to discuss a smart investing plan for a child or teenager. A household that needs spending control first should begin with budgeting and add investing education once the basics are stable.
Who should try it, and who should skip it
I would recommend trying it to parents who want a structured way to talk about long-term money habits without starting with an intimidating adult finance platform. It is especially promising for families that can commit to shared check-ins, explain unfamiliar terms, and adapt the routine to a child’s reading, attention, motor, or sensory needs.
I would be more cautious if a parent expects the app to teach everything automatically. The description of a smart investing plan may sound self-contained, but good financial understanding still comes from conversation and repetition. A child should know what the plan is intended to do, what it cannot promise, and why an adult is involved.
I would also skip it for a family seeking a purely hands-off solution, a detailed professional investing workstation, or an entertainment experience with constant rewards. Those expectations do not match the role I see here. The app is most useful as a bridge between adult guidance and a young person’s growing understanding.
Its public presence is still modest compared with the most familiar finance products: it has over one hundred thousand installs, an average rating of 4.5 from around three thousand ratings, and 534 written reviews. Those figures suggest encouraging interest, but I would still judge it by whether it fits the child’s needs instead of treating popularity as proof of accessibility or educational quality.
My inclusive verdict after using it
Acorns Early works best when I treat it as a shared family tool, not as a child’s independent financial adviser. Its free availability, Everyone age rating, and support for older Android versions make it approachable to try, while the family-focused purpose gives parents a reason to return to it with a real goal in mind.
The inclusive strength is its potential to make a complicated topic less intimidating. The inclusive limitation is that a friendly finance app still depends on reading, attention, device comfort, adult explanation, and access to a suitable routine. Families should test those practical details early and be willing to use spoken explanations, larger screens, paper notes, or shorter sessions.
My recommendation is to use it as a conversation starter with a clear family routine. If you want a simple path into saving and investing discussions for a child or teenager, it is worth exploring. If you need advanced adult investing controls, a tactile first lesson, or a complete budgeting system, another option may fit better. For the right household, its value is not that it removes every barrier; it gives parents a manageable place to begin and adapt the lesson around the young person.
Acorns Early is free, and the developer is Acorns. I would install it with realistic expectations, explore it before involving a child, and make accessibility part of the family plan from the first session rather than treating it as an afterthought.
Acorns Early: Kids Money App FAQ
What is Acorns Early: Kids Money App?
Acorns Early is a family-focused money app designed to help parents introduce children to saving, spending, and basic financial responsibility. Parents can typically create a supervised experience for their kids, assign money for chores or allowances, and monitor activity from their own account. The app is intended to make everyday money lessons more practical and engaging than simply explaining financial concepts.
What age group is Acorns Early designed for?
Acorns Early is generally aimed at children and teenagers who are ready to start learning how money works, although the most appropriate age can depend on the child’s maturity and the features available under the current plan. Parents should review the app’s age requirements, account rules, and regional availability before downloading. Younger children may need more direct parental guidance when using the app.
How do parents add money and manage their child’s account?
Parents manage the main account and control how money is provided to their children. Depending on the available features, this may include setting recurring allowances, rewarding completed chores, transferring funds, reviewing transactions, and adjusting spending controls. Before using the app, parents should check whether transfers are instant or scheduled, whether fees apply, and what verification steps are required to connect a funding source.
Is Acorns Early safe for children to use?
The app is built around parental supervision, which can make it a safer way for children to practice money management than using an unrestricted financial account. Parents should still review privacy permissions, notifications, spending controls, and transaction history regularly. It is also important to explain that the app is a learning tool, not a replacement for conversations about online safety, responsible spending, and protecting account credentials.
Does Acorns Early cost money, and is it available on Android and iPhone?
Acorns Early may be included with an eligible Acorns subscription or may depend on the plan selected, so pricing and access can change over time. Users should confirm the current terms in the official app listing or Acorns website before signing up. Availability can also vary by country, operating system, and account eligibility. Check the latest Android or iOS requirements before downloading.












